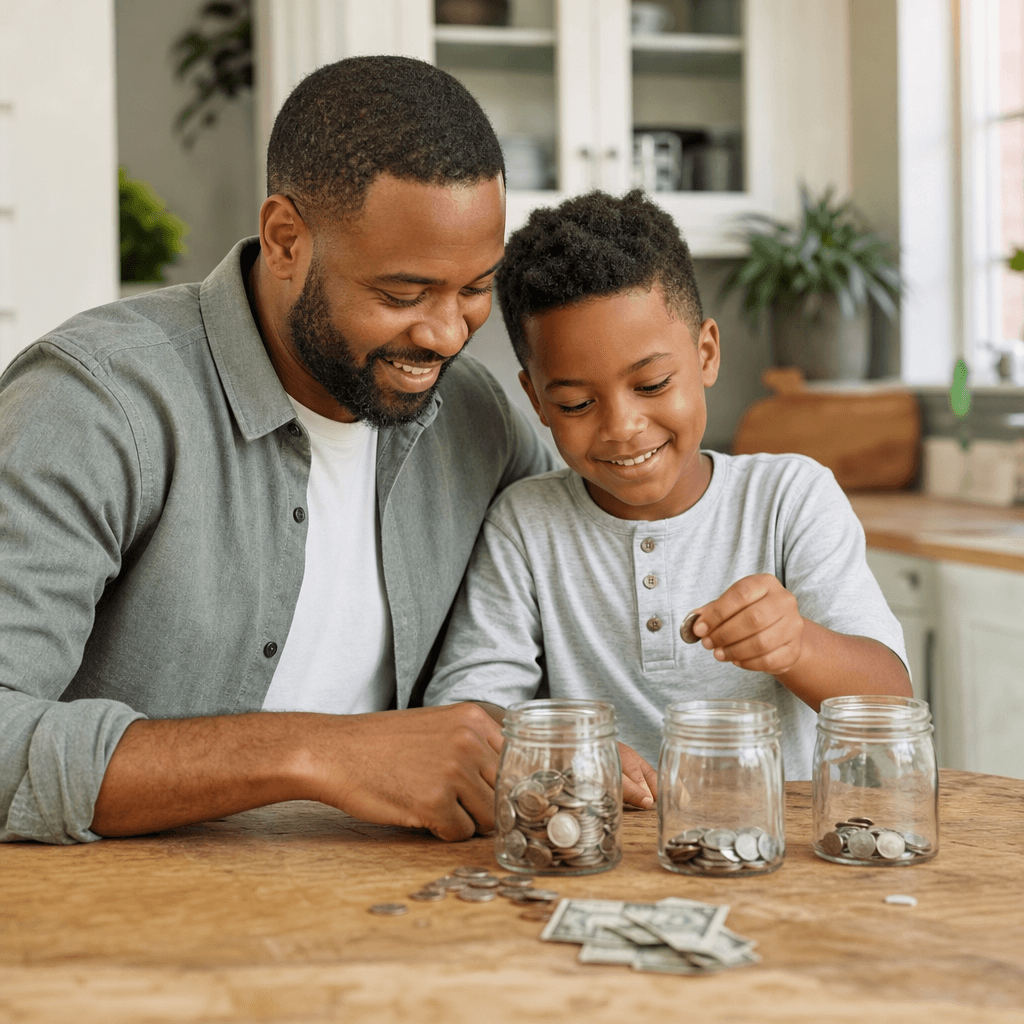
Many parents want kids to be “good with money” but freeze at the idea of a formal finance talk. The good news is that everyday money skills rarely start with a lecture. They start with small, repeated choices: waiting for something, comparing two prices, earning a bit of cash, and noticing that money spent on one thing cannot also buy another. Those moments are already happening at home. The work is to make them visible and discussable without turning dinner into a seminar.
This guide focuses on practical habits for elementary through early teen years. You do not need investment jargon. You need a calm tone, age-fit responsibilities, and a few routines that teach earning, saving, spending, and sharing through action.
What “Money Skills” Actually Means for Kids
For children, financial literacy is less about markets and more about four everyday capacities:
- Counting and comparing: Understanding amounts, change, and “more vs. less”
- Delaying gratification: Waiting, saving, and choosing later rewards
- Trade-offs: Seeing that every yes contains a no
- Responsibility: Caring for belongings and following through on small earning tasks
Adults often jump to credit scores and retirement. Kids need the foundation first. Strong foundations make later concepts easier to absorb.
Start With Language at the Store and Online Cart
Shopping is a natural classroom. Narrate a few choices out loud without performing:
- “We came for cereal and fruit. The snacks look fun, but they are not on the list today.”
- “This brand is cheaper per ounce. Let’s check if we actually like it.”
- “We can buy the game now, or wait two weeks and keep saving for the bigger one.”
Keep the tone matter-of-fact. Shame (“we’re too poor”) and impulse (“we deserve everything”) both teach the wrong lesson. Neutral trade-off language teaches better judgment.
A simple comparison habit
Once a week, let your child help compare two similar items. Ask which is a better fit for your family’s needs and why. The goal is reasoning, not always picking the cheapest option.
Give Money a Job With Clear Jars or Envelopes
Younger kids understand money better when it is visible. Use three containers:
- Spend: Small purchases they can choose
- Save: Medium-term goals with a picture of the target
- Give: Optional donations or gifts they care about
When cash or allowance arrives, split it immediately. The ritual matters more than the exact percentages. Over time, kids see progress toward a goal and feel the cost of dipping into savings early.
For older kids, a basic youth account or prepaid setup can work if you still review activity together. Visibility beats secrecy.
Tie Small Earnings to Real Contribution
Allowance policies differ by family. What matters is that money sometimes connects to contribution so kids do not treat cash as weather that simply appears.
Good earning tasks are concrete and finishable:
- Wash the family car interior
- Sort recycling for a month
- Help prep lunches on school nights
- Tutor a younger sibling on reading flashcards
Pay after the work meets the agreed standard. That sequence—effort, completion, payment—teaches more than a speech about “hard work.”
Avoid turning every kindness into a invoice. Family members help because they belong. Earning tasks sit beside unpaid contributions, not instead of them.
Practice Spending Decisions Before the Stakes Get High
Let kids make small purchases with their own Spend money—even if you would choose differently. A mildly disappointing toy that breaks early can be a better teacher than a perfect parental veto, provided you stay kind and skip “I told you so.”
Helpful reflection questions after a purchase:
- What did you like about it?
- Would you buy it again at the same price?
- If you saved one more week, what else could you have chosen?
Keep reflections short. The point is pattern recognition, not interrogation.
Teach Needs, Wants, and Waiting Without Moral Panic
Kids classify almost everything as a need. You can introduce a simple sort:
- Needs: Things required for health, school readiness, and safety
- Wants: Things that are enjoyable but optional
- Nice-to-wait: Wants that improve with time, research, or saving
Use examples from your own choices too. When adults admit “I want this, and I am waiting until payday,” kids see patience modeled instead of only demanded.
The 24-hour pause
For non-essential wants above a small threshold, require a one-day wait. Many urges fade. The ones that remain become cleaner save-vs-spend decisions.
Bring School Learning Home Without Homework Battles
If your child is learning percentages, averages, or unit rates, borrow those skills for home math:
- Unit price on two sizes of the same product
- A simple savings thermometer toward a goal
- Estimating the total before the cashier rings up
Keep it playful and brief. Two minutes of real-life math beats a worksheet tone at the kitchen table.
Age-Fit Ideas at a Glance
- Ages 5–7: Cash jars, store comparisons, waiting games with stickers toward a goal
- Ages 8–11: Allowance splits, small earning tasks, 24-hour pauses, basic budgeting for a family outing treat
- Ages 12–14: Goal tracking, comparing subscriptions, understanding advertising hooks, previewing how debit works with supervision
Match complexity to maturity. Curiosity is a better pace-setter than a curriculum checklist.
Closing: Make Money Talk Ordinary
Kids do not need a dramatic “money talk” as much as they need ordinary, respectful practice. Compare prices. Split earnings into jobs for money. Let small mistakes happen inside a safe budget. Model waiting without drama.
Over years, those tiny loops become judgment. A teenager who has practiced trade-offs with $15 decisions is better prepared for $150 ones. Start with the next shopping trip or the next allowance day. Keep it light, keep it consistent, and let real choices do most of the teaching.