Daftar isi: [Hide]
- 1What Is the ACA Subsidy Cliff?
- 2Why the Subsidy Cliff Is Coming Back in 2026
- 3Who Will Be Most Impacted?
- 4Why Premiums Could Rise Even Higher in 2026
- 5How Many People Could Lose Coverage?
- 6Could Congress Prevent the Subsidy Cliff?
- 7What Consumers Can Do Now to Prepare
- 8Conclusion: The ACA Subsidy Cliff Could Become a Crisis by 2026
- 9📌 The password is in the YouTube video : @ALMAZCANVAPRO (INVITE LINK PART 1) JOIN TEAM ✅
- 10ALTERNATIVE LINK IF YOU NEED TO BUY CHECK (LYNK.ID)

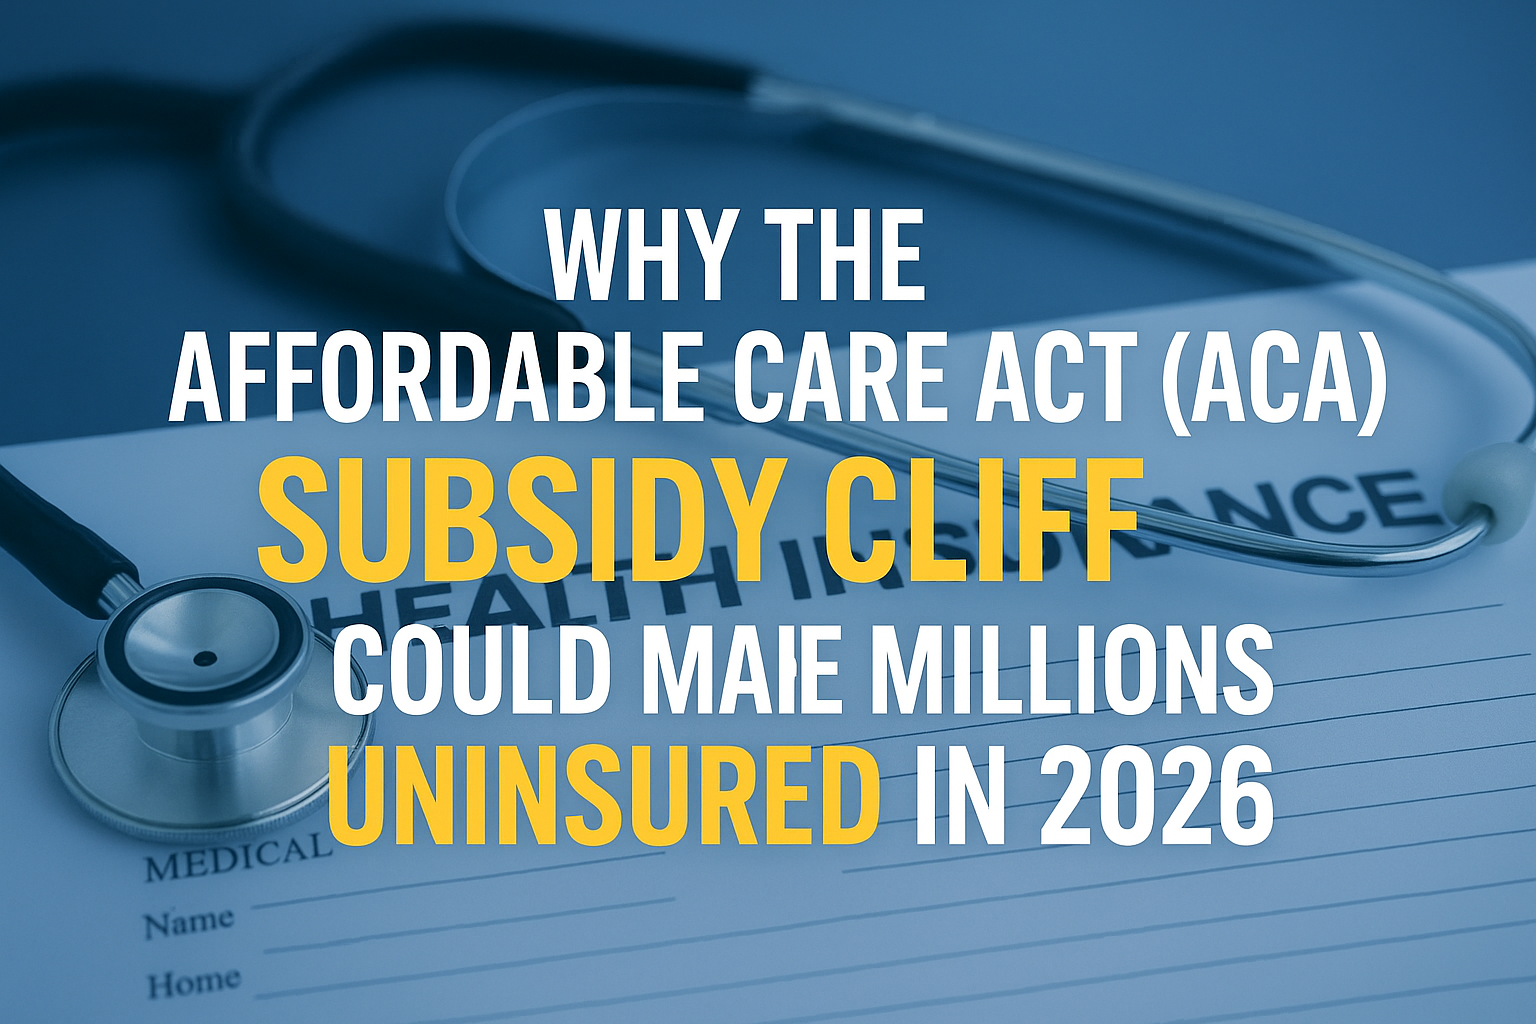
The Affordable Care Act (ACA) subsidy cliff is quickly emerging as one of the biggest threats to U.S. health coverage heading into 2026. While most Americans have benefited from expanded premium tax credits under the American Rescue Plan (ARP) and Inflation Reduction Act (IRA), those temporary boosts are set to expire soon. If Congress does not act, millions of Americans could face massive premium spikes, pushing many off the ACA marketplace entirely.
This issue has gained renewed attention as analysts warn that the 2026 subsidy cliff could reshape the health-insurance landscape—especially for middle-income families, gig-economy workers, and early retirees who rely heavily on ACA plans. With premiums already rising in 2025, the disappearance of enhanced subsidies could create a perfect storm that leaves many uninsured.
What Is the ACA Subsidy Cliff?
Under the ACA, premium tax credits are designed to make health insurance more affordable by limiting how much a household must spend on premiums relative to its income. However, until recent temporary laws altered the formula, subsidies abruptly ended at 400% of the Federal Poverty Level (FPL). That sudden cutoff is what experts call the subsidy cliff.
Normally, someone earning just below 400% FPL would qualify for substantial tax credits, while someone earning one dollar above that threshold would receive no assistance at all.
This created dramatic affordability gaps in the past:
- A family of three making $82,000 could receive several thousand dollars in subsidies.
- A family making $82,001 could receive zero, even though their actual insurance needs were identical.
Recognizing this imbalance, Congress temporarily removed the cliff through 2025, allowing subsidies to phase out gradually instead of disappearing instantly. But this relief is short-lived unless lawmakers extend it.
Why the Subsidy Cliff Is Coming Back in 2026
The enhanced subsidies introduced in 2021 were never permanent. They were designed as emergency measures to help Americans navigate pandemic-era financial challenges. Under current law:
- Enhanced subsidies expire at the end of 2025.
- In 2026, the old ACA subsidy formula returns, including the cliff at 400% FPL.
- Premium contributions will again be capped based on income—but only for those under 400% FPL.
This means millions who benefited from expanded assistance will face significantly higher premiums overnight.
According to policy estimates from multiple U.S. think tanks, if the subsidy cliff returns:
- Premiums could increase by $1,200–$4,000 per year for middle-income households.
- Early retirees (ages 55–64) could see increases of over $6,000 per year.
- Many families that currently pay under $100/month could see premiums jump to $400–$800 per month.
For many households, these increases simply won’t be affordable.
Who Will Be Most Impacted?
The return of the ACA subsidy cliff will not impact everyone equally. The groups most exposed include:
1. Middle-Income Families
These households earn above the 400% FPL threshold but still struggle with high insurance premiums—especially in states with limited competition.
In some states, ACA plans for a family of four can exceed $1,500–$2,000 per month without subsidies.
2. Self-Employed & Gig-Economy Workers
Freelancers, independent contractors, and startup entrepreneurs rely heavily on marketplace coverage. Without subsidies, many may be forced to choose between:
- High-deductible catastrophe plans
- Going uninsured
- Switching to limited-benefit plans (which may violate ACA standards)
3. Early Retirees (Ages 55–64)
Older Americans not yet eligible for Medicare face the steepest premium increases. Historically, this group suffered the most under the original subsidy cliff.
4. Families with Chronic Illness or High Medical Needs
For households with ongoing medical expenses, losing subsidies often puts ACA Silver and Gold plans out of reach.
If premiums double, some may opt for lower-quality alternatives, undermining long-term health outcomes.
Why Premiums Could Rise Even Higher in 2026
Even without the cliff returning, premiums have been rising due to:
- Medical inflation
- Rising hospital and pharmaceutical costs
- Increased demand for care post-pandemic
- Higher insurer payouts
- Continued instability in the individual market
Analysts expect average ACA premiums to increase 6–11% in 2026 before subsidies. When combined with the loss of enhanced tax credits, some consumers could see 25–40% higher net premium costs.
The result? A surge in uninsured Americans.
How Many People Could Lose Coverage?
Estimates vary, but most projections indicate that millions could lose coverage:
- The Congressional Budget Office (CBO) previously estimated that rolling back subsidies could increase the uninsured population by 3–4 million.
- Some independent policy groups estimate the number could be 5–8 million, depending on premium levels in 2026.
- Historically, subsidy cliffs have led to large coverage losses among early retirees and middle-income households.
Without intervention, this could become one of the largest insurance disruptions since the ACA’s launch.
Could Congress Prevent the Subsidy Cliff?
Yes—Congress has three options:
1. Extend the Enhanced Subsidies
This is the simplest approach. Congress has already renewed these subsidies once, so doing it again is possible—though increasingly uncertain due to political polarization.
2. Make the Enhanced Subsidies Permanent
This has strong support among consumer advocates but faces resistance due to the high federal cost (estimated $25–30 billion per year).
3. Create a Modified Subsidy Phase-Out
Instead of a sharp cliff, subsidies could taper slowly above 400% FPL. This would reduce premium shocks without requiring the full cost of current expanded subsidies.
Regardless of the solution, lawmakers must act before 2026 open enrollment begins. Once premiums are published, the effects will be felt immediately.
What Consumers Can Do Now to Prepare
While the policy future remains uncertain, Americans can take proactive steps:
✔ 1. Estimate Your 2026 Income Carefully
If your income might fall near the 400% FPL threshold, consider using IRS-approved strategies that legally reduce Modified Adjusted Gross Income (MAGI), such as:
- Contributions to traditional IRAs
- Contributions to Health Savings Accounts (HSAs)
- Retirement account deferrals
Lowering MAGI can help maintain eligibility for subsidies.
✔ 2. Explore Employer Coverage Options
Some employers are expanding benefits ahead of expected ACA volatility.
✔ 3. Review Alternative Coverage Options
Including:
- Medicare (if applicable)
- Medicaid (for eligible low-income families)
- High-quality short-term plans (state-dependent)
- Union or trade-association health plans
✔ 4. Monitor Legislative Updates
Because the decision will likely be political, staying informed is crucial for planning your 2026 insurance budget.
Conclusion: The ACA Subsidy Cliff Could Become a Crisis by 2026
The potential return of the ACA subsidy cliff is a direct threat to the stability of the U.S. health-insurance marketplace. Without congressional action, millions of Americans—especially those in the middle class—could face crushing premium increases that push them out of coverage entirely.
The stakes are high: financial security, access to healthcare, and national insurance coverage rates all hang in the balance.
Do you think Congress should extend the enhanced subsidies? Drop your thoughts in the comments!
📌 The password is in the YouTube video : @ALMAZCANVAPRO (INVITE LINK PART 1) JOIN TEAM ✅
ALTERNATIVE LINK IF YOU NEED TO BUY CHECK (LYNK.ID)