Daftar isi: [Hide]
- 1The Hidden Threat Facing Small Businesses in 2026
- 2What Is Cyber Insurance?
- 3Why Cyber Threats Are Increasing in 2026
- 4What Does Cyber Insurance Cover?
- 5What Cyber Insurance Does Not Cover
- 6How Much Does Cyber Insurance Cost in 2026?
- 7Real-World Example
- 8Industries That Need Cyber Insurance the Most
- 8.13Healthcare
- 8.14Financial Services
- 8.15E-Commerce
- 8.16Professional Services
- 8.17Education
- 8.18Technology Companies
- 9Benefits of Cyber Insurance
- 10Potential Drawbacks
- 10.23Premium Increases
- 10.24Coverage Restrictions
- 10.25Security Requirements
- 11How to Choose the Best Cyber Insurance Policy
- 11.26Evaluate Your Risks
- 11.27Compare Coverage Limits
- 11.28Review Exclusions
- 11.29Assess Insurer Expertise
- 11.30Examine Deductibles
- 11.31Verify Incident Response Support
- 12Cyber Insurance vs Cybersecurity
- 13The Future of Cyber Insurance
- 14Frequently Asked Questions
- 15📌 The password is in the YouTube video : @AERLAN (LINK RESMI PART 1) JOIN NOW ✅

The Hidden Threat Facing Small Businesses in 2026
Many small business owners assume cybercriminals only target large corporations. Unfortunately, that assumption is becoming increasingly dangerous. In 2026, small businesses are among the most frequent targets of ransomware attacks, phishing scams, data breaches, and other cyber threats.
The reason is simple: hackers often see small businesses as easier targets because they typically have fewer cybersecurity resources and less sophisticated protection systems than larger organizations.
A single cyberattack can lead to:
- Loss of customer data
- Business interruption
- Legal expenses
- Regulatory fines
- Reputation damage
- Recovery costs that can reach tens or even hundreds of thousands of dollars
This growing risk has made cyber insurance one of the most discussed business protection products in recent years.
But is cyber insurance for small businesses actually worth the cost in 2026?
The answer depends on your business, but for many companies, the benefits significantly outweigh the costs.
What Is Cyber Insurance?
Cyber insurance is a specialized policy designed to protect businesses against financial losses caused by cyber incidents.
Unlike traditional business insurance, cyber insurance specifically addresses digital risks such as:
- Data breaches
- Ransomware attacks
- Malware infections
- Business email compromise
- Identity theft
- Network security failures
- Customer notification costs
- Legal claims related to cyber incidents
As cyber threats continue evolving, cyber insurance has become an important component of a comprehensive risk management strategy.
Why Cyber Threats Are Increasing in 2026
Several trends are driving the rise in cybercrime:
1. AI-Powered Attacks
Cybercriminals now use artificial intelligence to create highly convincing phishing emails and fake communications.
These attacks can bypass traditional security awareness measures and trick employees into revealing sensitive information.
2. Remote and Hybrid Work
Many companies continue operating with remote employees.
While this provides flexibility, it also increases the number of access points available to attackers.
3. Cloud Dependency
Businesses rely heavily on cloud-based software and storage solutions.
Although cloud providers invest heavily in security, businesses remain responsible for protecting their own accounts, credentials, and customer data.
4. Ransomware Growth
Ransomware attacks remain one of the most profitable cybercrime methods.
Attackers encrypt company data and demand payment for restoration.
Without proper protection, recovery can be extremely costly.
What Does Cyber Insurance Cover?
Coverage varies between providers, but most policies include several core protections.
Data Breach Response
When customer data is exposed, businesses may need to:
- Investigate the breach
- Notify affected customers
- Provide credit monitoring services
- Hire legal advisors
Cyber insurance often covers these expenses.
Business Interruption
Cyberattacks can force businesses to temporarily shut down operations.
Policies may compensate for lost income during recovery periods.
Ransomware Payments
Some policies help cover ransomware-related expenses, including negotiation and recovery services.
Legal Defense Costs
Customers, vendors, or partners may file lawsuits after a cyber incident.
Cyber insurance often includes legal defense coverage.
Regulatory Fines
Depending on local laws and policy terms, certain fines and penalties may be covered.
Digital Asset Restoration
Coverage may include costs associated with recovering damaged files, databases, and systems.
What Cyber Insurance Does Not Cover
Business owners should understand the limitations of coverage.
Common exclusions include:
- Intentional misconduct
- Fraud committed by business owners
- Previously known vulnerabilities
- Poor security practices
- Certain contractual liabilities
- Acts of war or state-sponsored attacks
Reading policy details carefully is essential before purchasing coverage.
How Much Does Cyber Insurance Cost in 2026?
Cyber insurance pricing depends on several factors.
Factors Affecting Cost
- Industry type
- Company size
- Revenue
- Number of employees
- Data volume
- Security controls
- Claims history
- Coverage limits
Typical Cost Ranges
Small businesses may pay:
| Business Size | Estimated Annual Premium |
|---|---|
| Freelancer | $300–$800 |
| Small Company (1–20 employees) | $500–$2,500 |
| Growing Business (20–100 employees) | $2,000–$10,000+ |
Businesses handling sensitive customer information typically pay higher premiums.
However, compared to the potential financial impact of a major cyberattack, these costs are often considered reasonable.
Real-World Example
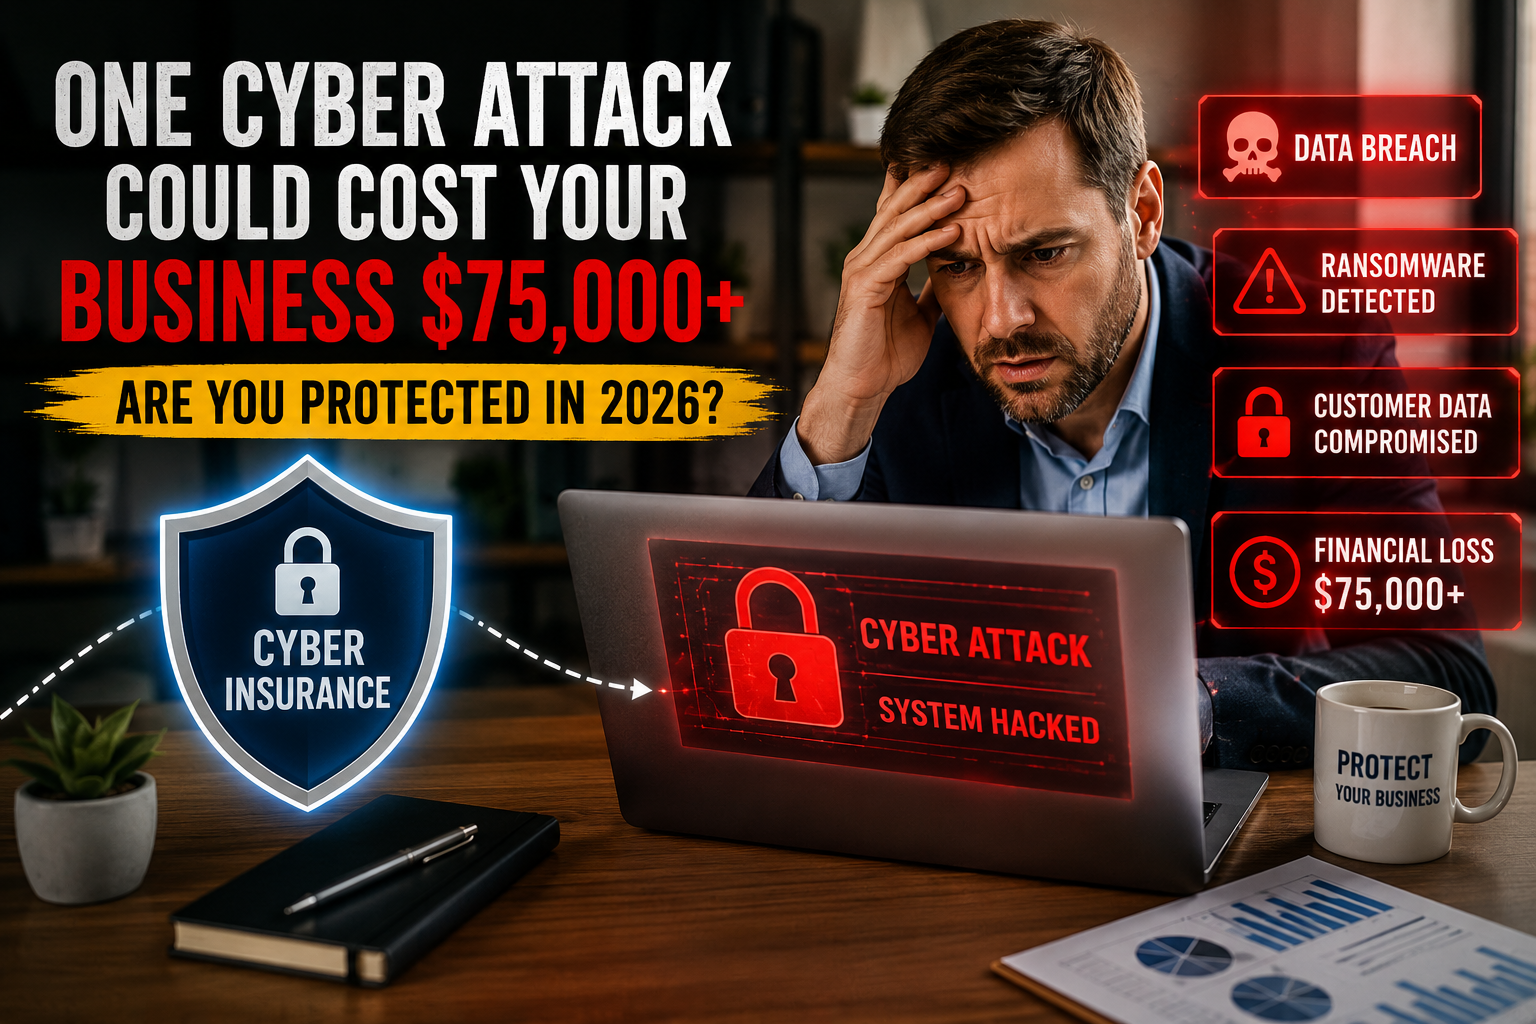
Imagine a small e-commerce company with annual revenue of $500,000.
An employee accidentally clicks a malicious email link.
Hackers gain access to customer information and deploy ransomware.
Potential expenses could include:
- Forensic investigation: $10,000
- Legal consultation: $15,000
- Customer notification: $5,000
- Business interruption losses: $20,000
- System restoration: $25,000
Total impact: $75,000+
A cyber insurance policy could help offset a significant portion of these costs.
Industries That Need Cyber Insurance the Most
While nearly every business faces cyber risk, some industries face particularly high exposure.
Healthcare
Medical records are highly valuable to cybercriminals.
Financial Services
Banks, advisors, and accounting firms handle sensitive financial information.
E-Commerce
Online retailers process customer payment data daily.
Professional Services
Law firms, consultants, and agencies store confidential client information.
Education
Schools and training providers maintain large databases of personal information.
Technology Companies
Software providers often manage sensitive customer systems and infrastructure.
Benefits of Cyber Insurance
Financial Protection
The primary advantage is reducing the financial impact of cyber incidents.
Access to Experts
Many insurers provide access to:
- Incident response teams
- Cybersecurity specialists
- Legal advisors
- Public relations professionals
Improved Risk Management
Insurance providers often require businesses to improve cybersecurity practices before issuing coverage.
This can strengthen overall security.
Customer Confidence
Having cyber insurance demonstrates a commitment to protecting customer data.
Potential Drawbacks
No insurance product is perfect.
Premium Increases
Cyber insurance costs have increased as cybercrime becomes more common.
Coverage Restrictions
Some policies contain strict conditions and exclusions.
Security Requirements
Businesses may need to implement:
- Multi-factor authentication
- Employee training
- Endpoint protection
- Backup systems
However, these requirements often improve security regardless of insurance benefits.
How to Choose the Best Cyber Insurance Policy
Evaluate Your Risks
Identify:
- Data types stored
- Customer information collected
- Critical business systems
- Potential attack scenarios
Compare Coverage Limits
Ensure coverage aligns with potential losses.
Review Exclusions
Understand what is not covered.
Assess Insurer Expertise
Choose providers with strong cyber incident response capabilities.
Examine Deductibles
Balance premium costs against out-of-pocket expenses.
Verify Incident Response Support
Rapid response can significantly reduce overall losses.
Cyber Insurance vs Cybersecurity
Many business owners mistakenly believe insurance can replace cybersecurity.
It cannot.
Cyber insurance should complement security measures rather than replace them.
Businesses should still invest in:
- Firewalls
- Endpoint protection
- Security monitoring
- Employee awareness training
- Backup systems
- Multi-factor authentication
Think of cybersecurity as prevention and cyber insurance as financial protection when prevention fails.
The strongest strategy combines both.
The Future of Cyber Insurance
The cyber insurance market continues evolving rapidly.
Trends expected throughout 2026 include:
- AI-driven risk assessments
- More customized policies
- Stricter underwriting requirements
- Expanded ransomware coverage
- Greater integration with cybersecurity platforms
Insurers increasingly reward businesses that maintain strong security practices.
This creates incentives for organizations to improve their cyber defenses.
Frequently Asked Questions
Is cyber insurance legally required?
No. Most businesses are not legally required to carry cyber insurance, but many organizations view it as an essential risk management tool.
Can small businesses afford cyber insurance?
Yes. Many policies are specifically designed for small businesses and offer affordable entry-level coverage.
Does cyber insurance cover ransomware?
Many policies provide ransomware-related coverage, although terms vary by provider.
Is cyber insurance worth it for a very small business?
Even businesses with only a few employees can experience significant financial losses from cyberattacks. Coverage may still provide valuable protection.
Can cyber insurance replace cybersecurity software?
No. Cyber insurance and cybersecurity tools serve different purposes and should work together.
Conclusion
Cyber threats are no longer a problem reserved for large corporations. In 2026, small businesses face increasingly sophisticated attacks that can cause substantial financial and operational damage.
For many organizations, cyber insurance for small businesses is absolutely worth considering. The cost of coverage is often far lower than the potential expense of recovering from a serious cyber incident.
The best approach combines strong cybersecurity practices with an appropriate cyber insurance policy. Together, they create a powerful defense against one of the fastest-growing business risks in today’s digital economy.
What do you think? Has your business considered cyber insurance in 2026? Share your experience or questions in the comments below!
📌 The password is in the YouTube video : @AERLAN (LINK RESMI PART 1) JOIN NOW ✅
ALTERNATIVE LINK IF YOU NEED TO BUY CHECK (LYNK.ID) R̶p̶ ̶9̶5̶,̶0̶0̶0̶ Only Rp 5.000 (CLICK HERE)
̶
OR YOU CAN CHECK VIA SHOPEE (CLICK HERE)