Daftar isi: [Hide]
- 1Introduction
- 1.1Finance
- 1.2Healthcare
- 1.3Manufacturing
- 1.4Human Resources
- 1.5Customer Service
- 21. Algorithmic Bias
- 32. Privacy Violations
- 43. Intellectual Property Claims
- 54. Incorrect Business Decisions
- 65. Hallucinations
- 7Legal Defense Costs
- 8Third-Party Liability
- 9Regulatory Investigations
- 10Professional Liability
- 11Media and Intellectual Property Claims
- 12Business Interruption
- 13Financial Services
- 14Healthcare
- 15Technology Companies
- 16Manufacturing
- 17Retail and E-commerce
- 17.6Company Revenue
- 17.7AI Usage
- 17.8Industry
- 17.9Compliance Programs
- 17.10Security Controls
- 17.11Claims History
- 18Inventory Your AI Systems
- 19Review Existing Insurance
- 20Establish AI Governance
- 21Strengthen Cybersecurity
- 22Evaluate Third-Party Vendors
- 23What is AI Liability Insurance?
- 24Is AI Liability Insurance different from Cyber Insurance?
- 25Which companies should buy AI Liability Insurance?
- 26Does AI Liability Insurance cover generative AI?
- 27Can small businesses benefit from AI Liability Insurance?

Introduction
Artificial intelligence has evolved from an experimental technology into a core business capability. Large enterprises now rely on AI to automate operations, improve customer experiences, optimize supply chains, detect fraud, develop software, and support executive decision-making.
As AI adoption accelerates, organizations are also discovering an uncomfortable reality:
The legal risks associated with AI are growing just as quickly.
A single AI mistake can trigger:
- Multi-million-dollar lawsuits
- Regulatory investigations
- Customer claims
- Intellectual property disputes
- Privacy violations
- Business interruption
- Reputation damage
Traditional insurance policies were never designed for autonomous decision-making systems or generative AI.
This gap has fueled the rapid emergence of AI Liability Insurance, a specialized form of commercial coverage designed to help businesses manage the legal and financial consequences of AI-related incidents.
This guide explains everything enterprise decision-makers need to know before purchasing AI Liability Insurance in 2026.
What Is AI Liability Insurance?
AI Liability Insurance is a commercial insurance product that protects organizations against financial losses arising from the design, deployment, operation, or use of artificial intelligence systems.
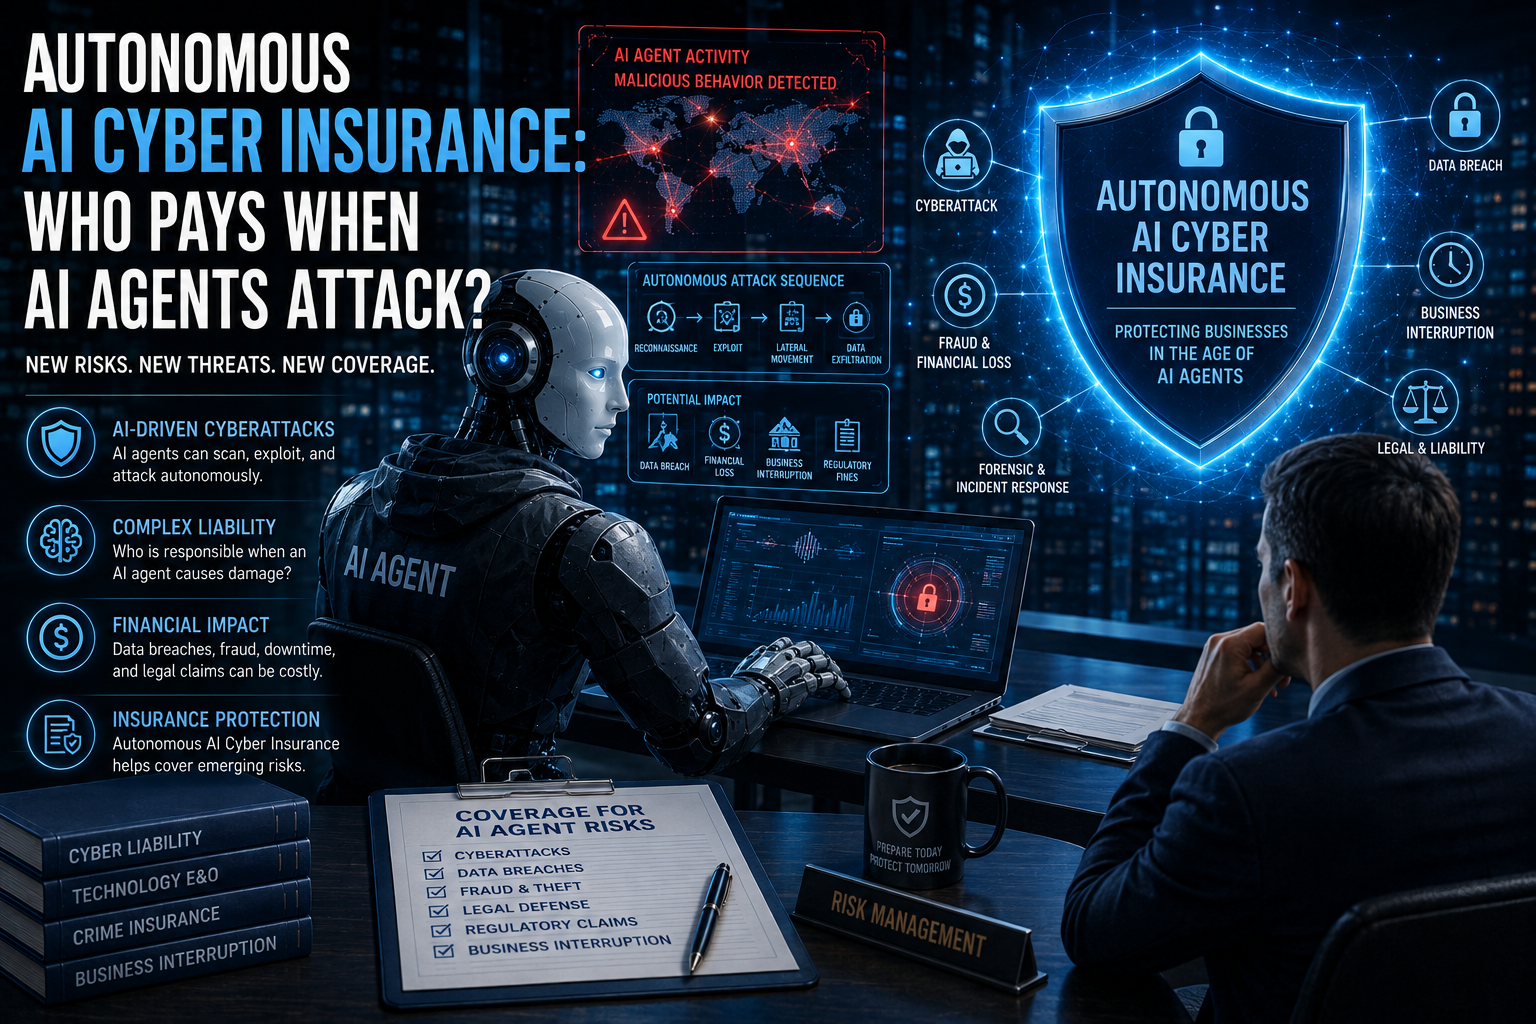
Unlike standard cyber insurance, AI Liability Insurance addresses a broader set of risks, including:
- Algorithmic decision failures
- AI-generated misinformation
- Bias and discrimination claims
- Intellectual property disputes
- Privacy violations
- Regulatory investigations
- Professional negligence
- Third-party financial losses
The objective is to reduce the financial impact of AI-related legal disputes while supporting business continuity.
Why Enterprise Businesses Need AI Liability Insurance
Large organizations typically use AI across multiple departments.
Examples include:
Finance
- Credit scoring
- Fraud detection
- Investment recommendations
- Risk modeling
Healthcare
- Diagnostic support
- Medical imaging
- Patient triage
- Clinical decision support
Manufacturing
- Predictive maintenance
- Robotics
- Quality inspection
- Supply chain optimization
Human Resources
- Candidate screening
- Workforce planning
- Performance analytics
Customer Service
- AI assistants
- Intelligent chatbots
- Voice automation
- Personalized recommendations
Every deployment increases operational efficiency—but also expands liability exposure.
The Biggest AI Liability Risks Facing Enterprises
1. Algorithmic Bias
One of the most significant legal concerns involves discrimination.
If an AI hiring platform unintentionally disadvantages certain applicants, the organization could face:
- Employment lawsuits
- Regulatory action
- Civil penalties
- Reputation damage
2. Privacy Violations
AI often processes enormous amounts of personal information.
Improper collection, storage, or use of data can expose organizations to:
- Privacy litigation
- Regulatory fines
- Customer compensation claims
3. Intellectual Property Claims
Generative AI systems may produce content that resembles copyrighted works.
Potential disputes involve:
- Copyright infringement
- Trademark misuse
- Trade secrets
- Licensing conflicts
4. Incorrect Business Decisions
Agentic AI systems may autonomously:
- Approve loans
- Execute transactions
- Reject insurance claims
- Optimize pricing
Errors can generate substantial financial losses for customers or business partners.
5. Hallucinations
Even advanced AI models occasionally generate inaccurate information.
When enterprises rely on these outputs for legal, financial, or healthcare decisions, the consequences may be severe.
How AI Liability Insurance Works
Most policies begin with a detailed underwriting process.
Insurers assess:
- AI governance maturity
- Internal controls
- Human oversight
- Security practices
- Regulatory compliance
- Incident response capabilities
- Vendor management
- Claims history
Based on these factors, insurers determine:
- Coverage limits
- Premiums
- Exclusions
- Deductibles
Organizations with mature AI governance often receive more favorable terms.
What Does AI Liability Insurance Cover?
Coverage varies by insurer, but policies may include:
Legal Defense Costs
Legal representation can become extremely expensive.
Coverage often includes:
- Attorney fees
- Court costs
- Expert witnesses
- Settlement negotiations
Third-Party Liability
If AI causes financial harm to customers or partners, insurance may respond to covered claims.
Regulatory Investigations
Some policies help cover:
- Government inquiries
- Administrative proceedings
- Compliance defense costs
Professional Liability
Coverage may apply when AI-powered professional services contribute to client losses.
Media and Intellectual Property Claims
Certain policies include protection for:
- Copyright disputes
- Trademark claims
- Defamation allegations
- AI-generated content issues
Business Interruption
Operational failures involving AI systems can disrupt revenue-generating activities.
Some policies provide financial support during covered interruptions.
What AI Liability Insurance Usually Does NOT Cover
Policy wording differs, but common exclusions may include:
- Intentional misconduct
- Criminal activity
- Contractual guarantees
- Known incidents before policy inception
- Failure to maintain minimum security controls
- War and terrorism
- Certain regulatory penalties where prohibited by law
Businesses should review exclusions carefully before purchasing coverage.
AI Liability Insurance vs. Cyber Insurance
| Feature | AI Liability Insurance | Cyber Insurance |
|---|---|---|
| Data breaches | Sometimes | Yes |
| Ransomware | Limited | Yes |
| Algorithmic bias | Yes | Usually No |
| AI decision errors | Yes | Usually No |
| Regulatory investigations | Often | Sometimes |
| Intellectual property disputes | Often | Rarely |
| AI-generated misinformation | Yes | No |
| Network security incidents | Limited | Yes |
Many enterprises benefit from carrying both policies because they address different categories of risk.
Industries That Benefit Most
Financial Services
Banks, lenders, fintech firms, and investment managers rely heavily on AI for lending, fraud detection, and portfolio analysis.
Healthcare
Hospitals, insurers, pharmaceutical companies, and digital health providers increasingly depend on AI for diagnosis, administration, and research.
Technology Companies
Software vendors and AI platform providers face direct exposure if their products malfunction or generate harmful outputs.
Manufacturing
Industrial AI supports robotics, predictive maintenance, and quality control, creating new operational liabilities.
Retail and E-commerce
Retailers use AI for dynamic pricing, recommendation engines, inventory planning, and customer support.
Factors That Affect Premium Costs
Premiums vary depending on:
Company Revenue
Larger organizations typically pay higher premiums because of greater exposure.
AI Usage
The more business-critical AI becomes, the greater the potential risk.
Industry
Highly regulated industries often face higher underwriting scrutiny.
Compliance Programs
Organizations with strong governance may qualify for lower premiums.
Security Controls
Robust cybersecurity measures reduce insurer risk.
Claims History
Previous incidents can significantly influence pricing.
Best Practices Before Buying a Policy
Inventory Your AI Systems
Identify every AI application used across the organization.
Review Existing Insurance
Determine whether current policies contain:
- AI exclusions
- Silent AI risks
- Coverage overlaps
Establish AI Governance
Implement:
- Human oversight
- Ethical review
- Risk committees
- Documentation standards
Strengthen Cybersecurity
Secure AI infrastructure with:
- Multi-factor authentication
- Continuous monitoring
- Encryption
- Access controls
Evaluate Third-Party Vendors
Many AI risks originate from external software providers.
Vendor due diligence should include contractual and insurance reviews.
Questions to Ask Before Purchasing AI Liability Insurance
Before selecting a policy, ask your insurer or broker:
- Does the policy explicitly cover AI-related liabilities?
- Are generative AI systems included?
- Does coverage extend to third-party AI vendors?
- Are regulatory investigations covered?
- What exclusions apply to autonomous AI systems?
- Does the policy include intellectual property protection?
- Is global coverage available?
- How are claims involving AI-generated decisions evaluated?
These questions can help avoid costly surprises after a claim.
Future Trends in AI Liability Insurance
The market is evolving rapidly. Over the next several years, enterprises can expect:
- More specialized AI insurance products
- Dynamic underwriting using real-time AI risk metrics
- Integration with AI governance frameworks
- Coverage tailored for Agentic AI and autonomous systems
- Expanded protection for AI-driven supply chains
- Greater emphasis on explainability and auditability
Organizations that invest early in governance and risk management are likely to benefit from broader coverage and more competitive premiums.
Frequently Asked Questions
What is AI Liability Insurance?
AI Liability Insurance protects businesses against certain legal, financial, and operational risks associated with artificial intelligence systems.
Is AI Liability Insurance different from Cyber Insurance?
Yes. Cyber Insurance primarily covers cyberattacks and data breaches, while AI Liability Insurance focuses on harms arising from AI decisions, outputs, and operations.
Which companies should buy AI Liability Insurance?
Organizations that develop, deploy, or rely heavily on AI—especially in regulated industries or customer-facing applications—should evaluate this type of coverage.
Does AI Liability Insurance cover generative AI?
Some policies do, but coverage varies significantly. Businesses should review policy wording carefully.
Can small businesses benefit from AI Liability Insurance?
Yes. While enterprise organizations often have greater exposure, smaller businesses that use AI extensively may also benefit from specialized coverage.
Conclusion
Artificial intelligence is reshaping the modern enterprise, bringing unprecedented opportunities for innovation, efficiency, and competitive advantage. At the same time, it introduces complex legal, operational, and regulatory risks that traditional insurance policies may not fully address.
AI Liability Insurance has emerged as a critical component of enterprise risk management, helping organizations prepare for disputes involving algorithmic decisions, intellectual property, privacy, professional liability, and regulatory scrutiny.
The most resilient businesses in 2026 will not simply adopt AI—they will also build strong governance, implement robust security controls, review vendor relationships, and ensure their insurance strategy evolves alongside their technology.
By taking a proactive approach today, enterprises can embrace AI innovation with greater confidence while reducing the financial impact of tomorrow’s uncertainties.
Authority Outbound Links
How is your organization preparing for AI-related liability risks? Share your insights or questions in the comments below.